Quick answer, as of September 2026
Reviewed September 9, 2026: evaluate Gulf Breeze by the address, duty route and complete property budget. The hypothetical $1,450 in monthly extras becomes $17,400 over a year. Actual taxes, coverage, condition and association obligations must be checked for the home you choose.
Gregg Costin, Realtor, Levin Rinke Realty
Key takeaways
- Confirm the parcel jurisdiction before relying on local rules.
- Check flood and evacuation information separately.
- Compare total ownership costs with your own income and reserves.
- Verify future rental use before relying on it as a PCS exit.
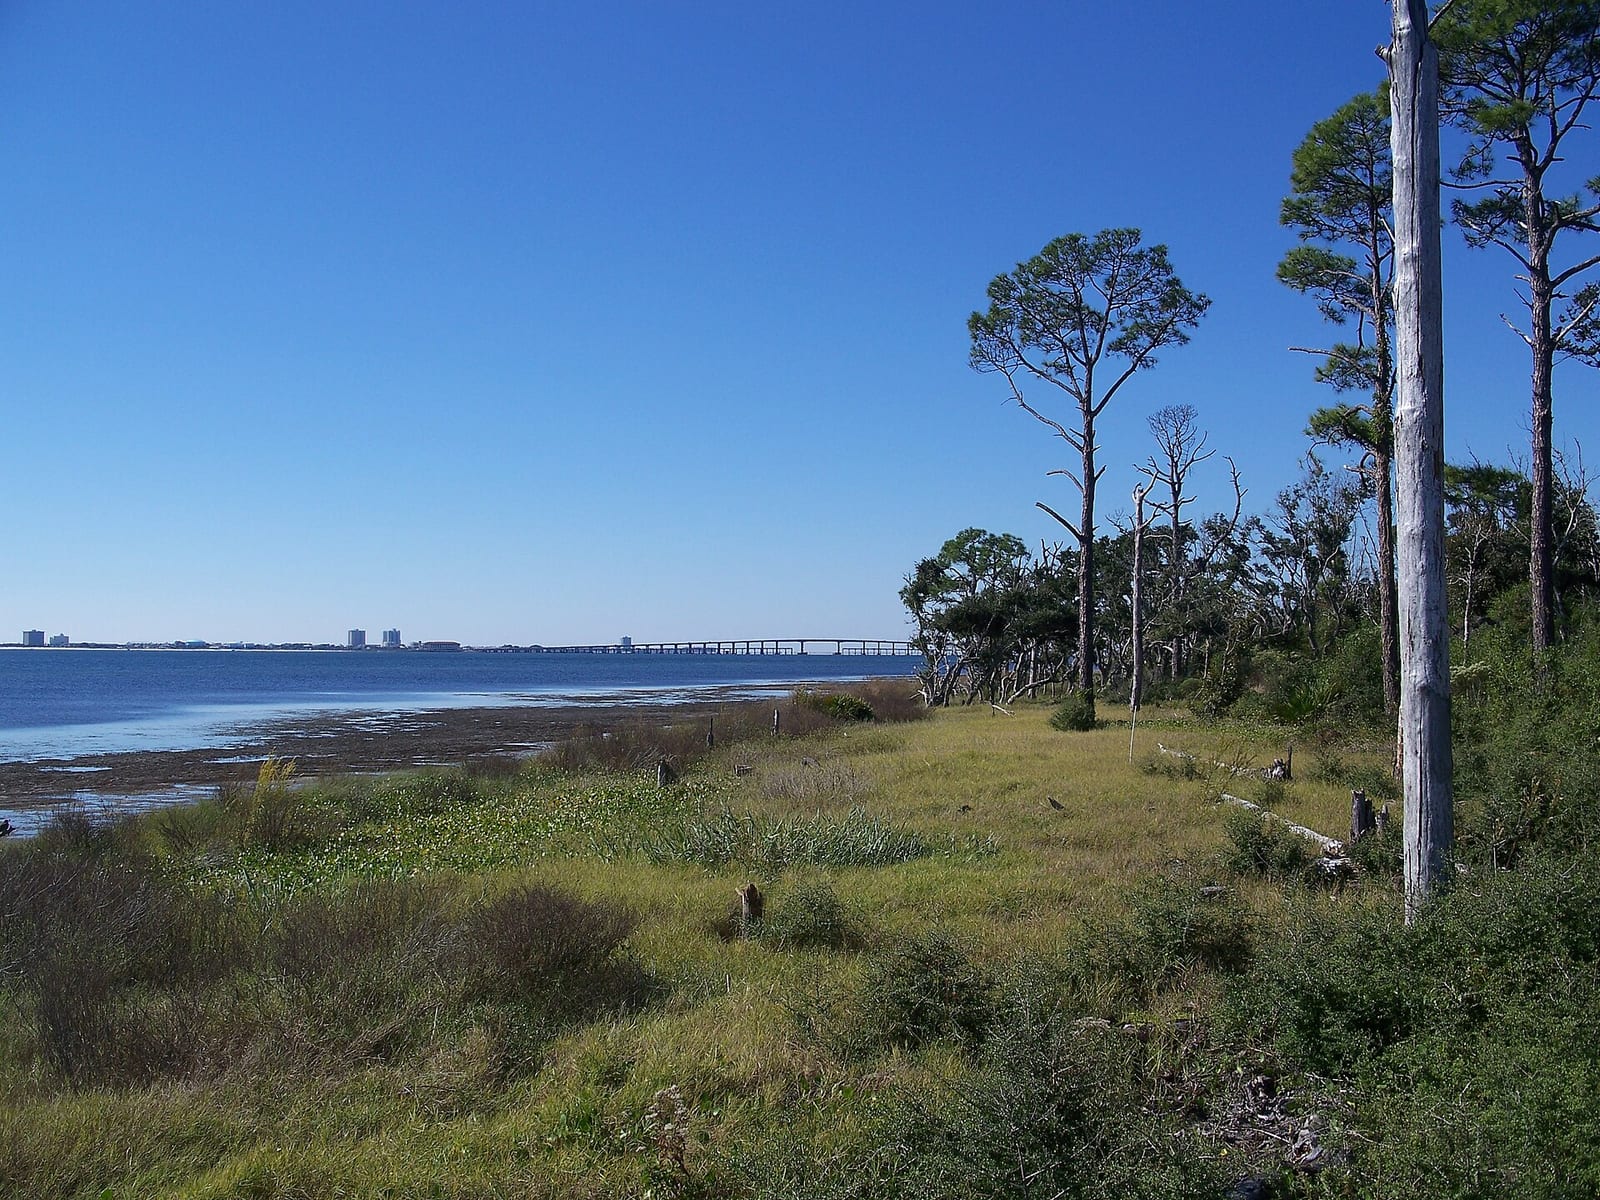
Gulf Breeze can be appealing when you want access to the coast while staying connected to the Pensacola area. For a military household, the decision becomes more concrete: does the address work for the duty route, the property budget and the way your household spends an ordinary week?
The name on a mailing address is not enough information. Separate the municipality, the broader search area and the individual parcel. Then ask what you are paying for, what you would give up and whether the plan remains workable if orders change. That produces a more useful answer than a generic list of pros and cons.
Which Gulf Breeze maps should you check before buying?
The City of Gulf Breeze publishes separate flood, hurricane evacuation, zoning and future-land-use maps. Start with its official GIS resources. The city cautions that mapping does not replace surveys, deeds or other legal instruments.
Confirm whether the parcel falls within the city or another jurisdiction before relying on a municipal rule or service assumption. Ask who provides water, sewer or septic oversight and other services. A Gulf Breeze mailing address should begin that investigation, not end it.
For an address in the broader Santa Rosa County search area, county Development Services is a starting point for planning, permitting and floodplain questions. Identify the responsible office before asking whether a particular renovation or future rental use is allowed.
Does being outside a high-risk flood zone remove the concern?
Flooding can occur outside mapped high-risk zones, and most homeowners insurance excludes flood damage. The National Flood Insurance Program explains that distinction. Obtain property-specific flood information and coverage advice before deciding what risk to retain.
Read the flood map and evacuation information as answers to different questions. Ask about the structure's elevation, prior damage disclosures, drainage and the documents an insurer needs. A view of the water cannot establish either safety or an insurance premium, and a listing's coverage estimate is not a policy issued to you.
Use the military insurance guide to organize the quote request. Compare coverage limits, roof treatment, exclusions and deductibles along with annual cost. An affordable premium can still leave a loss exposure larger than the cash reserve you planned to keep.
How much can the ownership extras change the budget?
In this hypothetical Gulf Breeze comparison, a household starts with a $2,350 loan payment and discovers that the full property budget is substantially larger. All expense inputs are invented. The example is a way to organize quotes, not a price estimate for Gulf Breeze or a recommendation to spend that amount.
| Category | Assumed monthly amount |
|---|---|
| Principal and interest | $2,350 |
| Buyer-based property tax | $400 |
| Homeowners and wind premium | $325 |
| Flood premium | $100 |
| Association dues | $75 |
| Maintenance reserve | $300 |
| Utilities | $250 |
| Expenses beyond principal and interest | $1,450 |
| Total monthly illustration | $3,800 |
The hypothetical $1,450 in monthly extras becomes $17,400 over a year. This example assumes no mortgage insurance or special assessment and excludes purchase cash, furnishing and travel expenses. Add those where applicable instead of treating a missing line as a verified zero.
The categories are consistent with CFPB's ownership-budget guidance. Use the actual-income worksheet to determine your own spending room. BAH is part of a household income picture, not proof that every property with a similar mortgage payment is affordable.
How should you test the military commute?
Test the complete route from the candidate home to the actual duty destination at your likely work times. For a NAS Pensacola household considering Gulf Breeze, include the bridge crossing, authorized gate and travel beyond the gate. A weekend trip to the waterfront does not answer the workday question.
For a household assigned to Hurlburt Field, compare the eastward route from that exact Gulf Breeze address with alternatives farther along the corridor. Use Florida 511 for current road conditions, then check both travel directions. No current commute duration has been measured for this article.
Write down the consequences of the route, not just its estimated minutes. Consider report-time reliability, another household member's work, appointments, school pickup and essential errands. A larger home can be a poor trade if its location makes the routine difficult to maintain.
What are the real advantages and tradeoffs?
The advantages depend on how much you value the particular property and its access to places you use. The tradeoffs are the costs, route constraints and property obligations required to obtain those benefits. You can prefer Gulf Breeze without assuming that every address offers the same experience.
- Location: Visit the places that matter to your household from the actual home.
- Property: Compare layout, condition and outdoor space with the work needed to maintain them.
- Budget: Price the house, coverage and recurring charges together.
- Flexibility: Consider how easily the plan adapts to a shorter assignment.
The Gulf Breeze community guide provides local context. Compare it with the Gulf Breeze versus Navarre guide and the Pensacola guide. Keep the same must-have criteria when evaluating the alternatives so a change in scenery does not silently change the budget.
What if you want to rent the home after PCS?
Treat future rental use as a separate decision requiring verification. Ask the appropriate jurisdiction and association about the proposed use, then obtain property-specific insurance, financing and management guidance. A nearby vacation rental does not establish permission, demand or a sustainable return for this address.
Distinguish a long-term tenant, a furnished mid-term arrangement and a short-term vacation rental. Each needs its own expense and operating plan. Include management, vacancy, turnover, maintenance and replacement reserves. Keep a downside case that does not assume uninterrupted bookings or free labor from a household stationed elsewhere.
The military rental-management guide and rent-or-sell decision guide help with that next step. If the purchase only works with optimistic future rent, revisit the price or the housing choice before using a possible exit as the reason to buy.
What should you verify before making an offer?
Bring the unresolved questions into the offer discussion early enough to investigate them. Good due diligence is specific: a missing roof record, an unconfirmed service connection or an unclear association obligation needs its own follow-up. A general statement that the house looks well maintained does not answer those questions.
- Confirm jurisdiction and the parcel's records.
- Check flood, evacuation and drainage information separately.
- Obtain comparable insurance and buyer-tax estimates.
- Review condition, permits and association documents.
- Test the duty route and household schedule.
- Compare your holding period with sale or rental costs.
Sources and References
City and county resources, NFIP, CFPB and Florida 511 were reviewed September 9, 2026. The budget figures are hypothetical and independently recomputed. This guide does not assign a flood status, school, permitted use, insurance premium or travel time to an unexamined property.
Frequently Asked Questions
Does a Gulf Breeze address mean the property is inside the city?
Do not assume it does. Confirm the parcel and jurisdiction through official records before relying on a city rule or service. The broader search area and mailing address can lead to different assumptions. Ask the responsible office about the exact property and the use you are considering.
Is Gulf Breeze a practical choice for NAS Pensacola?
It can be, depending on the address, reporting location and household schedule. Test the entire route at your expected work times, including the bridge and authorized gate. Compare the return trip and essential errands as well. A convenient weekend visit does not establish a dependable daily commute.
Can a home outside a high-risk flood zone still need flood coverage?
Yes. Flood risk exists outside mapped high-risk areas, and standard homeowners coverage usually excludes flood damage. Review the actual parcel and discuss appropriate coverage with an insurance professional. A lender requirement and the amount of risk you are comfortable retaining are separate parts of the decision.
What expenses should I add to the mortgage payment?
Include buyer-based taxes, homeowners and wind premiums, flood coverage, association charges and any applicable assessments or mortgage insurance. Add maintenance reserves and utilities for the broader budget. Keep cash to close and immediate repairs separate so the monthly total does not conceal a shortage of available cash.
Can I turn a Gulf Breeze home into a vacation rental later?
Verify that proposed use before relying on it. The responsible jurisdiction, association, insurance and financing arrangements can each matter. Obtain property-specific advice and an operating estimate. A nearby rental listing does not prove permission or profitability for your house, and expected bookings should not replace a reserve.
How should I compare Gulf Breeze with Navarre?
Use the same household requirements and cost categories for actual properties in both areas. Test the duty route, confirm coverage and inspect condition. Then compare what each location offers your routine and the next move. Avoid changing the budget assumptions merely because one listing is more visually appealing.
Put this guide to work
Bring the Gulf Breeze address, duty location and questions still missing answers.